AlaskaInsurance Appraiser (844) 537-1427

Independent claim appraisal · Statewide

Alaska Insurance Appraiser for disputed and underpaid property claims

When the insurer accepts your claim but the estimate won’t cover the repair, Alaska Insurance Appraiser builds an independent, line-by-line valuation and takes it through the appraisal clause in your policy.

Free claim review

30borough & census-area equivalents covered
12appraisal & estimating services
7free in-browser claim tools
2 of 3signatures make an award binding

Why owners call

The gap between “covered” and “paid in full”

Most disputed claims in Alaska aren’t denials. They’re estimates that leave things out: the insulation behind the wet drywall, the steep charge on a snow-country roof, the barge freight to Kodiak, the second course of ice and water shield. Alaska Insurance Appraiser exists for that gap.

As an Alaska Insurance Appraiser, we start from our own inspection and measurements, never from an edited copy of the carrier’s numbers. The goal is a valuation that holds up in front of an umpire, because that is what actually moves an award.

  • Retained by you. An Alaska Insurance Appraiser you appoint, independent of the carrier.
  • Priced for the place. Freight, travel and seasonal access included where they apply.
  • Honest triage. If you need an attorney or a supplement instead, we’ll say so.
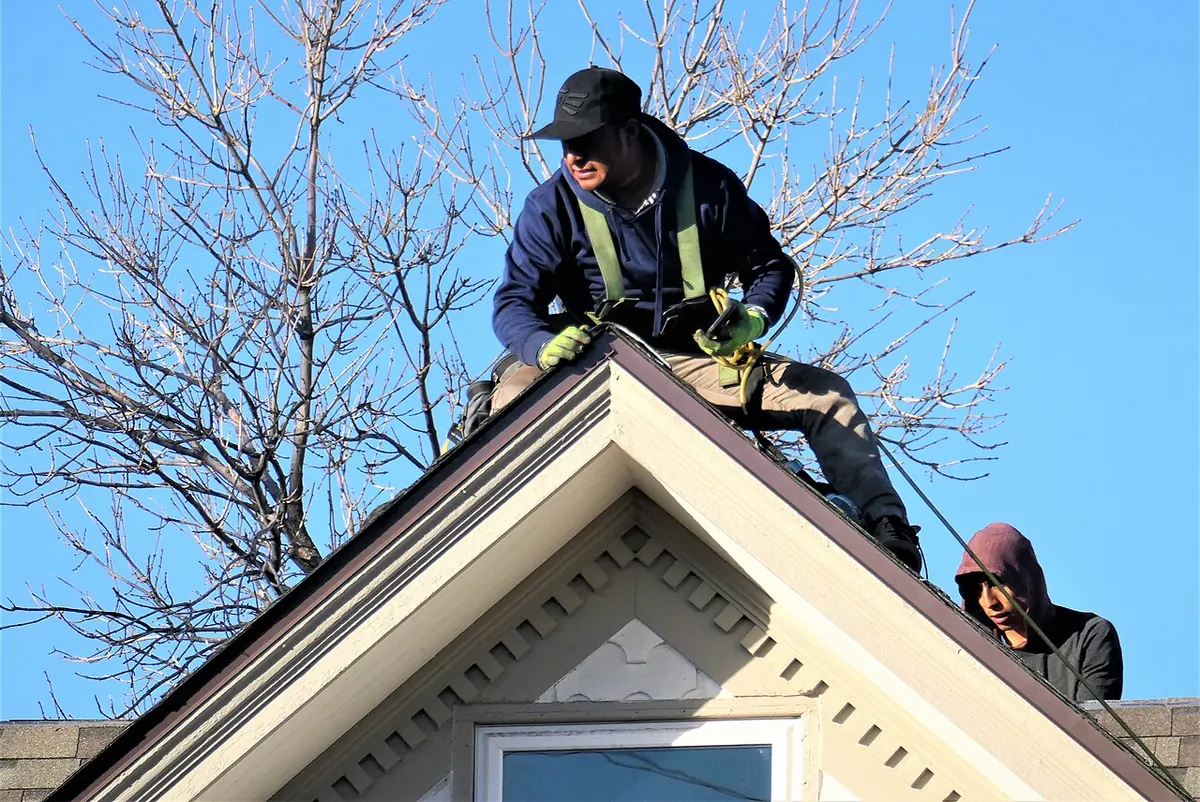
Roofer in a safety harness working along the ridge of a steep gable roof
Every estimate starts with our own measurements.

Services

Twelve ways Alaska Insurance Appraiser works on a claim

From a quick estimate review to full appraisal panel work and neutral umpire appointments, each service is built around one job: an accurate, defensible number for your loss.

Appraisal Panel Representation

We act as the appraiser you name once the appraisal clause has been invoked, from first inspection to signed award.

Learn more

Homeowner Claim Appraisal

Independent valuation of disputed dwelling, other-structure and contents losses for Alaska homeowners and condo owners.

Learn more

Commercial, HOA & Condo Appraisal

Appraisal and valuation support for businesses, landlords, condo associations and multifamily owners.

Learn more

Roof, Hail & Ice Damage Appraisal

Roof claim valuation for wind, ice, snow and the occasional hail event, including metal and low-slope roofs.

Learn more

Windstorm Damage Appraisal

Valuation of damage from downslope, gap and coastal winds, including roofs, siding, fences and fallen trees.

Learn more

Snow Load & Ice Dam Claims

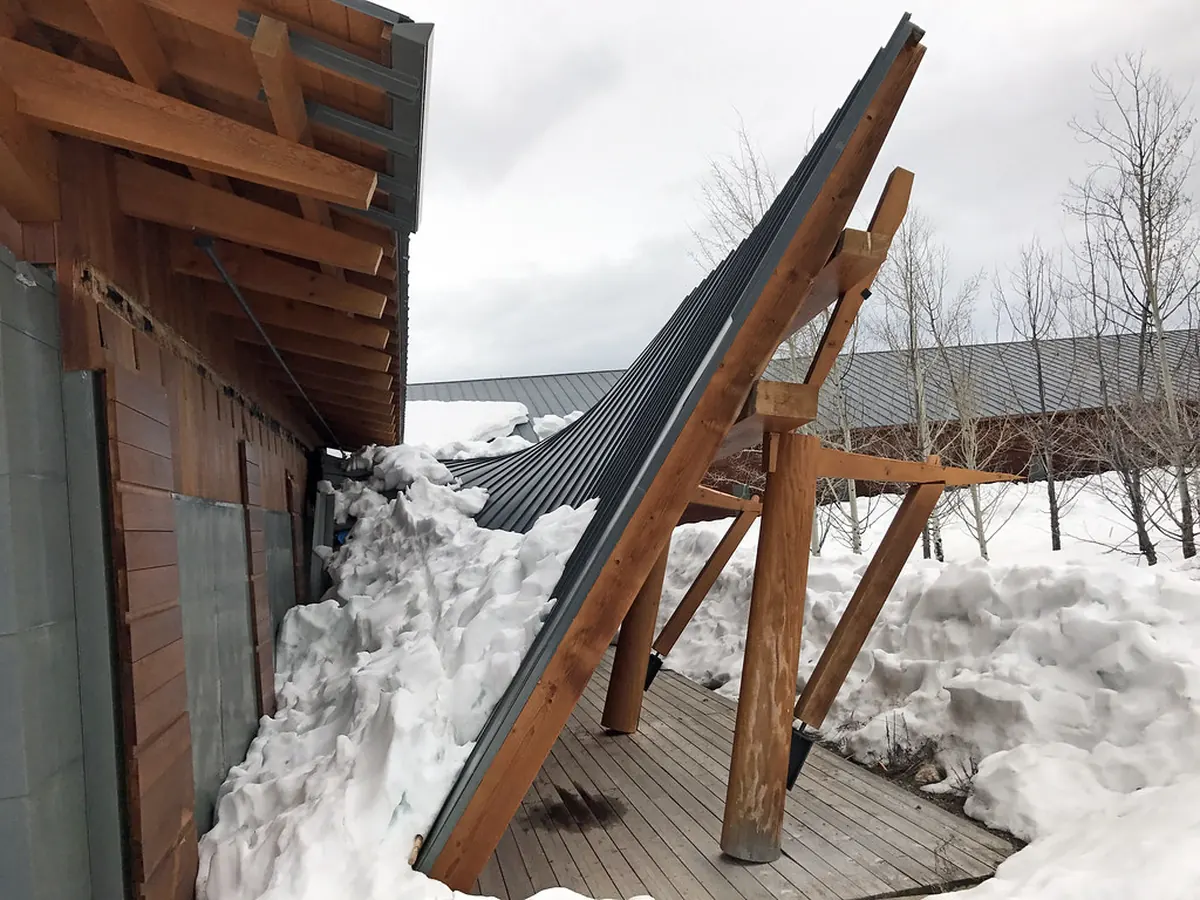
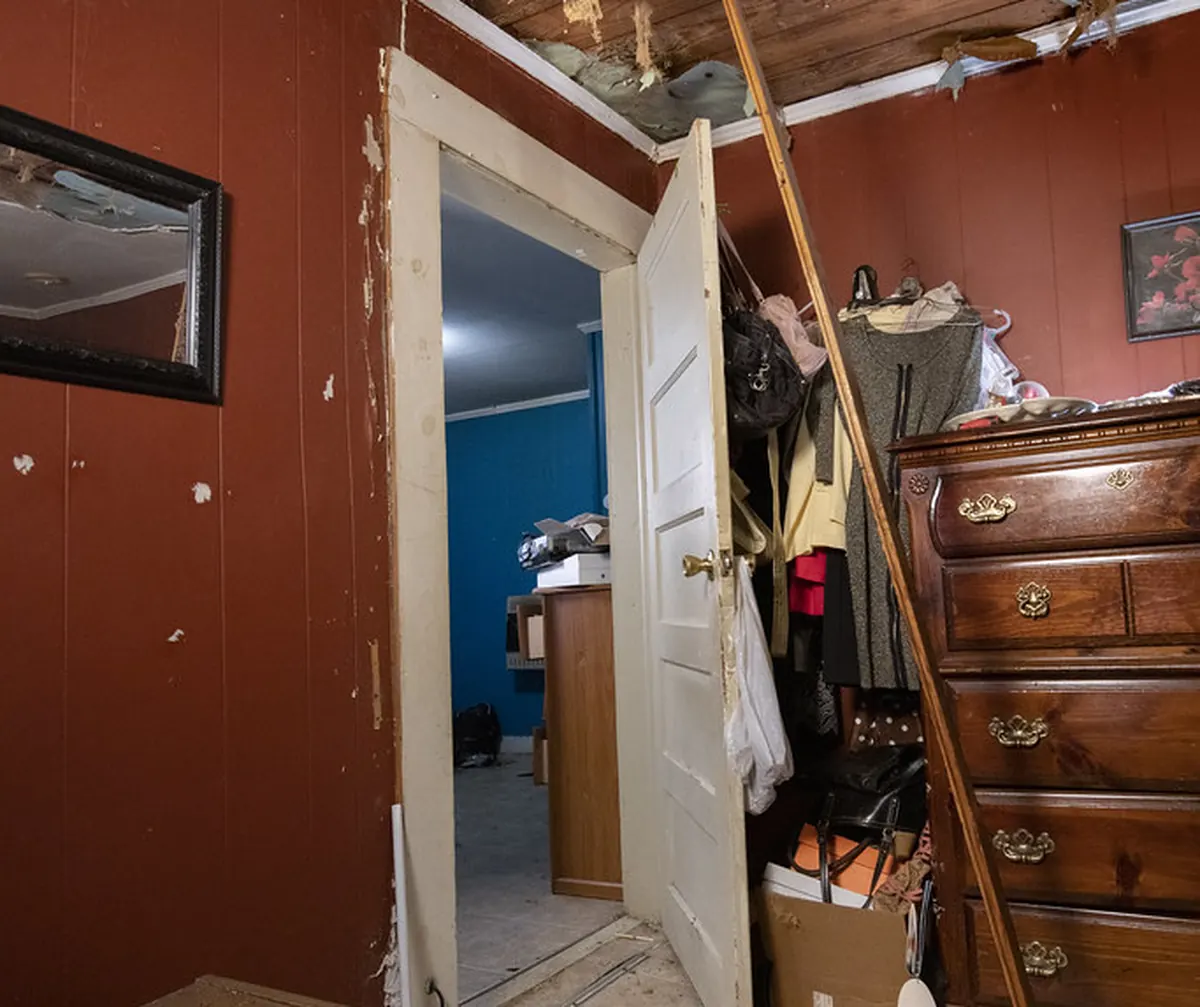
Appraisal of roof collapse, framing deflection and interior water damage caused by heavy snow and ice dams.

Learn more

Frozen Pipe & Water Damage Appraisal

Valuation of water losses from freeze-ups, burst lines, boilers and appliance failures, including drying and mold.

Learn more

Fire, Smoke & Wildfire Appraisal

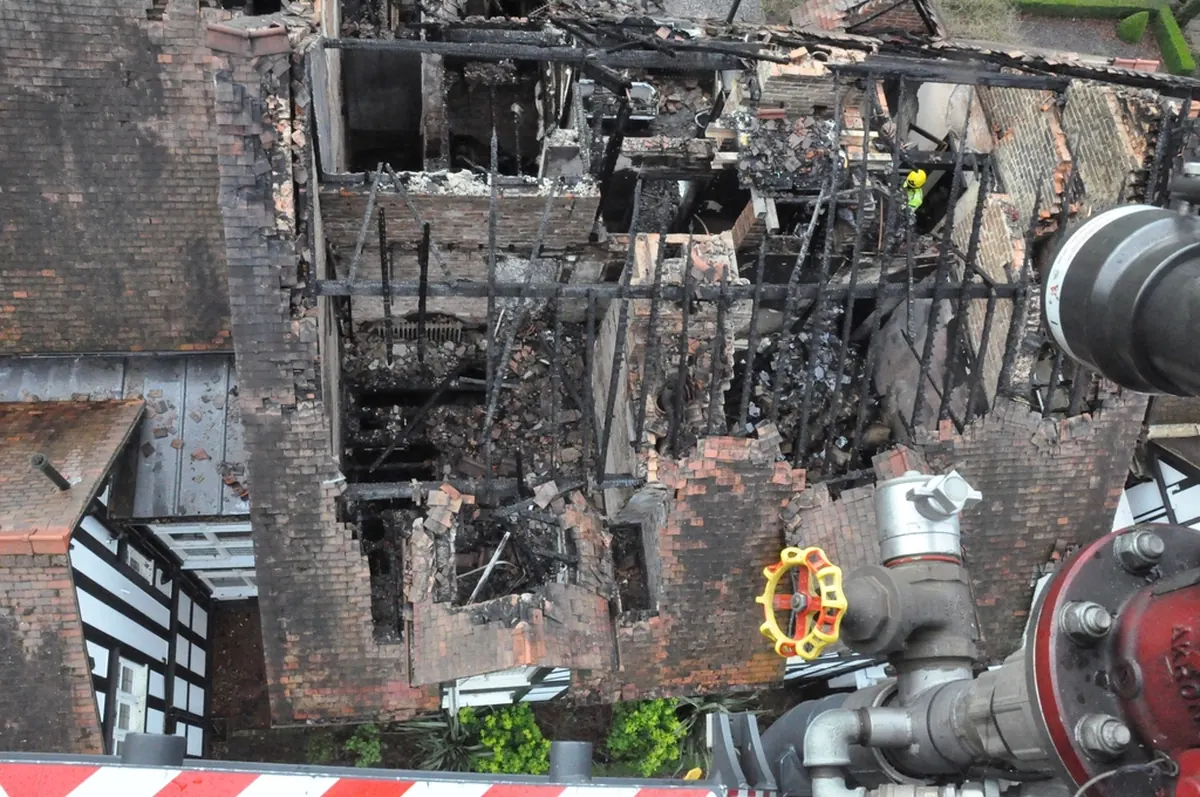
Appraisal of structure fires, chimney and stove fires, and wildfire smoke and ash damage.

Learn more

Earthquake Endorsement Claims

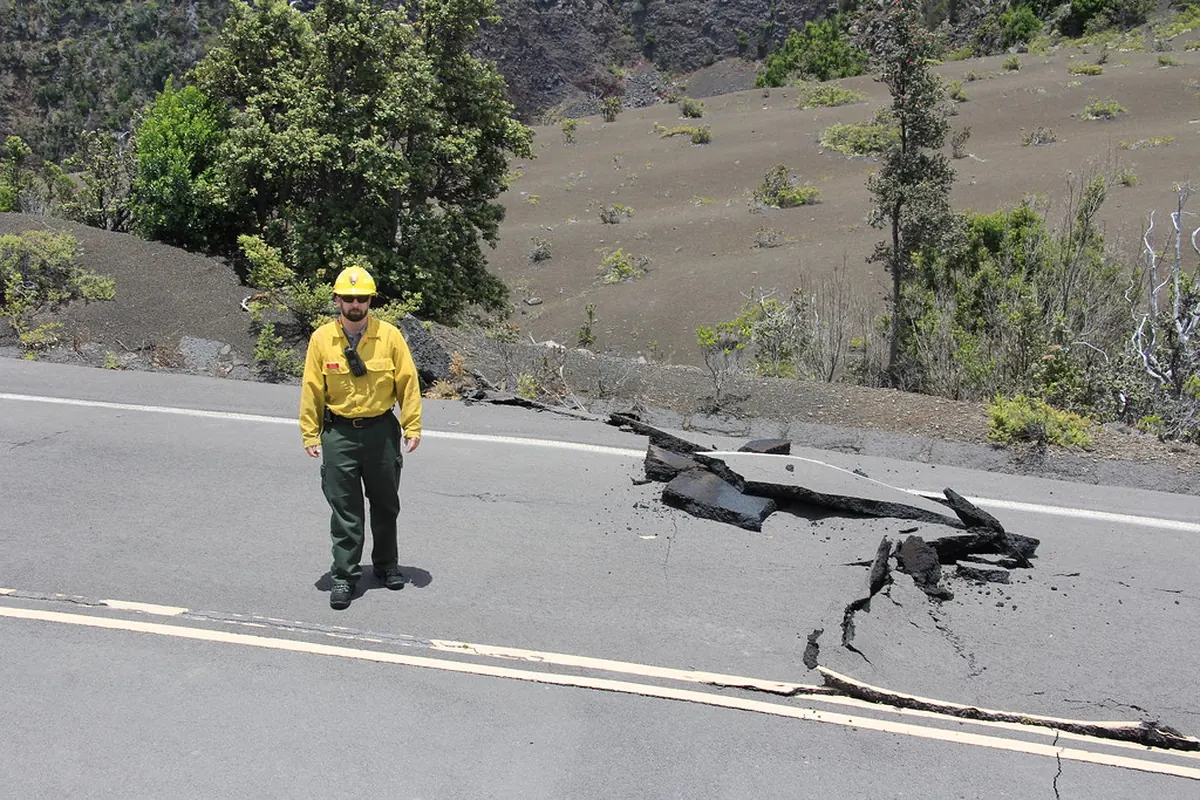
Valuation support for owners who carry earthquake coverage and disagree with the carrier's damage estimate.

Learn more

Remote & Off-Road-System Properties

Claim valuation for cabins, lodges and homes reached by plane, boat, barge or seasonal road.

Learn more

Carrier Estimate Review

A line-by-line review of the insurer's estimate that shows what is missing, underpriced or miscalculated.

Learn more

Neutral Umpire Services

Impartial umpire work for appraisal panels that cannot agree, for policyholders and carriers alike.

Learn more

When an Alaska Insurance Appraiser is the right call

  • Coverage accepted, cost disputed
  • Repair-versus-replace arguments
  • Discontinued siding, metal panels or flooring
  • Missing code items, steep charges or overhead and profit
  • Freight and travel left out for remote properties

When you probably need someone else

  • Outright denials based on an exclusion
  • Claims-handling or bad-faith concerns
  • Flood, surge or erosion with no flood policy
  • A gap too small to justify fees
  • A suit deadline that is close

How it works

From first call to signed award

The appraisal clause turns an open-ended disagreement into a defined process. Here is the path Alaska Insurance Appraiser follows once a demand is made.

  1. 1

    Send a written demand

    Follow your policy's appraisal clause. Most require a written demand. Keep a copy and proof of delivery.

  2. 2

    Name the appraisers

    Each side appoints its own appraiser, often within a set number of days of the demand. Your appraiser should meet the policy's independence requirement.

  3. 3

    Select an umpire

    The two appraisers try to agree on a neutral umpire. If they cannot, many policies let either side ask a court in the state where the property is located to appoint one.

  4. 4

    Appraisers work the differences

    The appraisers inspect, exchange estimates and go line by line. Most items are usually resolved at this stage.

  5. 5

    Umpire decides what is left

    Remaining items go to the umpire with supporting photos, measurements and pricing. The umpire may inspect the property.

Read the full eight-step guide

One state, five claim climates

How Alaska weather shows up in an estimate

Forty-below freeze-ups in Fairbanks, Taku winds in Juneau, wildfire smoke in the Mat-Su and earthquakes under Anchorage. An Alaska Insurance Appraiser has to price each one differently.

Southcentral & Mat-Su

Anchorage · Eagle River · Wasilla · Palmer

  • Earthquake (with coverage)
  • Downslope & Matanuska winds
  • Snow load
  • Wildfire

Most of the state’s population and most of its claims. The 2018 earthquake, Hillside and Matanuska windstorms and heavy-snow winters all show up here.
Interior

Fairbanks · North Pole · Delta Junction

  • Forty-below freeze-ups
  • Rain on snow
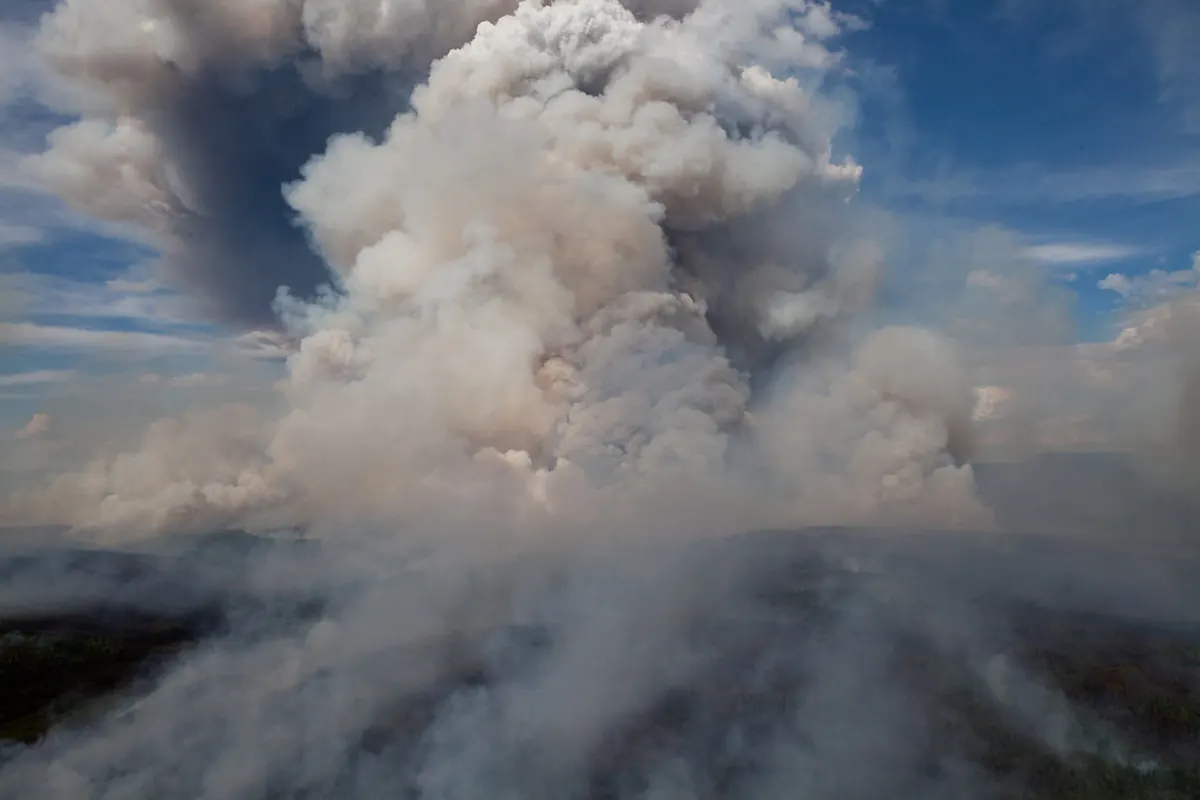
  • Wildfire smoke
  • Chimney fires

Extreme cold turns a heating failure into a whole-house water loss. Summers bring wildfire smoke across the Tanana Valley.

Southeast

Juneau · Ketchikan · Sitka

  • Heavy rain
  • Taku & Gulf winds
  • Glacial outburst floods
  • Landslides

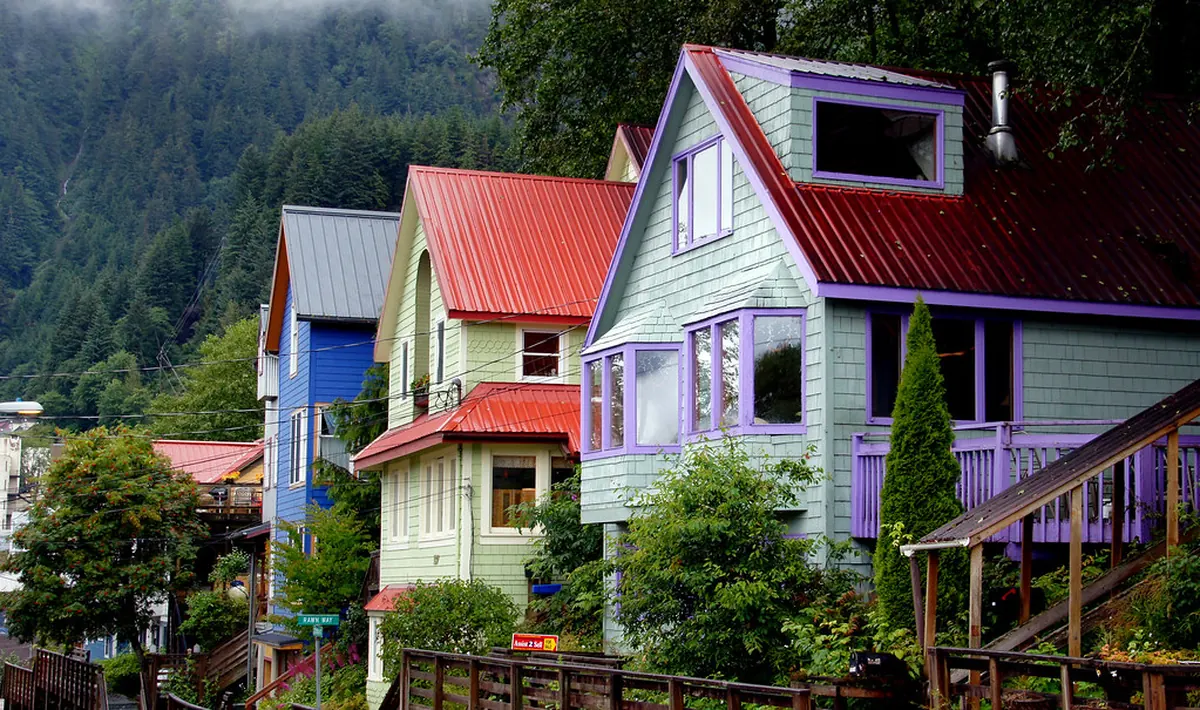
Steep, wet and barge-supplied. Water intrusion, wind and difficult access drive the cost of nearly every repair.

Kenai Peninsula & Kodiak

Kenai · Soldotna · Homer · Kodiak

  • Wildfire
  • Coastal wind
  • Volcanic ash
  • Earthquake (with coverage)

Beetle-killed spruce, coastal storms and Cook Inlet volcanoes. Island and end-of-road locations raise repair costs.

Western & Arctic

Bethel · Nome · Utqiagvik · villages

  • Ex-typhoon storms
  • Extreme cold
  • Fire
  • Remote logistics

Off the road system, freight and travel can rival the repair itself. Flood and erosion are usually excluded; wind, fire and interior water are not.

Quick gap check

Is your gap worth an appraisal?

Enter the two numbers you already have. If the difference is large, a conversation with an Alaska Insurance Appraiser makes sense. If it is small, a documented supplement request may close it faster and for less.

The full gap and fee estimator adds appraiser, umpire and travel costs for a realistic net figure.

Quick gap checkNo sign-up
50%
of the disputed amount
Amount in dispute$0
Gap vs. carrier estimate
—
Projected award
$0
Increase before fees
$0

Communities served

Alaska Insurance Appraiser, from Ketchikan to Fairbanks

We work in all 19 organized boroughs and across the Unorganized Borough. These are the communities where Alaska Insurance Appraiser handles claims most often.

Choosing help

Appraiser, public adjuster or attorney?

Each solves a different problem. Alaska Insurance Appraiser will point you elsewhere when appraisal isn’t the right tool.

Alaska Insurance Appraiser

Values the amount of loss

  • Best when: coverage accepted, number disputed
  • Result: binding award on the amount
  • Decides coverage: no

Public adjuster

Presents and negotiates the claim

  • Best when: early, from first notice
  • Result: negotiated settlement
  • Licensed by: Alaska Division of Insurance

Attorney

Handles legal disputes

  • Best when: denials, bad faith, deadlines
  • Result: settlement or judgment
  • Decides coverage: argues it in court

FAQ

Questions people ask an Alaska Insurance Appraiser

Straight answers about the process, the cost and when appraisal is the wrong move.

What does an Alaska Insurance Appraiser do?

We value property damage when you and your insurer agree the loss is covered but disagree on what it costs. As your appointed appraiser we inspect, build an independent line-item estimate, work with the carrier’s appraiser and, if needed, present unresolved items to a neutral umpire.

Is the appraisal award binding?

On the amount of loss, generally yes, once any two of the three panel members sign. That is why the documentation going in matters so much.

How is an appraiser different from a public adjuster?

A public adjuster presents and negotiates the whole claim. An appraiser works inside the policy’s appraisal clause on one question, the amount of loss. We don’t negotiate outside appraisal and we don’t give legal advice.

Do you work outside Anchorage?

Yes. We work statewide, including the Mat-Su, the Interior, Southeast, the Kenai Peninsula, Kodiak and communities off the road system. Remote inspections are planned around weather and access.

What does it cost?

Each side pays its own appraiser and usually half of the umpire. Our fee is agreed in writing before work starts, and the first conversation is free.

Does Alaska have a FAIR plan?

No. Alaska doesn’t operate a FAIR plan or a wind pool. Owners who can’t find standard coverage often use the surplus lines market. Appraisal clauses appear in most standard and surplus lines property forms.

Claim guides

Read before you invoke appraisal

Practical guides from Alaska Insurance Appraiser on policy language, documentation and Alaska-specific costs.

All guides

Start with a conversation

Talk to an Alaska Insurance Appraiser about your claim

Tell us what happened and what the carrier offered. We’ll review it and give you a straight answer on whether appraisal is worth pursuing.

Tell us about your claim

Free review, no obligation. We usually reply within one business day.

Call Free review